Property finance
Homes, investments and commercial
- Home loans and first home buyers
- Investment property loans
- Commercial property finance →
- SMSF loan refinance →
- SMSF business premises lending →
Buying an office, warehouse, shop or your own premises?
Commercial lending works differently from residential. Lenders look at the lease and the tenant as well as you, deposits are usually bigger, and the right owner, whether that’s you, a trust, a company or your SMSF, matters from day one.
ONE CONVERSATION · BOTH LENSES
With Vineet Danwar, Chartered Accountant & Mortgage Adviser
Most people juggle a broker, an accountant and a business adviser who never talk to each other. At TransformBiz it all sits with one team, so your loans, structures and business finance are planned together.
Homes, investments and commercial
Funding to run and grow the business
The thinking behind every loan
Credit services are provided under our Australian Credit Licence. Tax positions are confirmed with your accountant or registered tax agent, and SMSF decisions with a licensed financial adviser; we work alongside them.
For investors buying for rental income, and business owners buying their own premises outside super.
For trustees who, with their licensed adviser, have decided to buy business real property in the fund.
If you’ve only borrowed for homes or residential investments, commercial finance can catch you off guard. These are the four things we see buyers underestimate most.
Lenders assess the tenant, the lease term remaining and the rent, not just your income. A strong lease can open better options; a vacant or short-lease property narrows them.
Commercial lenders usually lend a lower share of the property’s value than residential lenders, so more of your own money or equity is needed. Policy varies widely between lenders.
Whether the sale is GST-free as a going concern, and which entity buys, affect the cash you need at settlement. Your accountant confirms the tax position; we build the lending around it.
For qualifying commercial property, Victoria’s commercial and industrial property tax means duty is paid one final time on entry, then an annual tax applies after a 10-year transition. Factor both into your numbers.
General information as at November 2026. Commercial lending is subject to lender policy and approval. Victorian duty and CIPT rules depend on the property’s use and the transaction; confirm with your accountant or conveyancer.
From 10 August 2026, a new SMSF limited recourse borrowing arrangement (LRBA) can only be used to buy business real property: generally, property used wholly and exclusively in a business, such as commercial premises. Residential property can no longer be bought with new SMSF borrowing.
The property must keep meeting the business real property rules for the life of the loan. If its use changes, the arrangement can breach the rules, so we plan for that from the start.
A related business can generally lease business real property from the fund, on commercial terms at market rent. Your SMSF accountant and adviser confirm the arrangement.
Contributions and rent have to cover repayments and costs, with a buffer left in the fund. We model that before any lender sees the application.
An SMSF purchase uses a holding (bare) trust, specialist lenders and documents that must line up. We coordinate the lender side with your accountant, adviser and solicitor.
“Banks will not issue loans against every trust structure, a detail I never knew and one that is often overlooked.”
“Vineet understands internal financial traits that could create significant issues later during the financing or acquisition stages. … The team is super proactive.”
“Most brokers arrange a loan. Vineet plans the structure behind it.”
“He positioned our portfolio properly and in the right order, and when the budget turned the market upside down, that groundwork is what protected us — we came through it secure, with our borrowing capacity largely preserved. … Genuinely strategic advice, not just finance.”
“Their understanding of finance, combined with their strong accounting knowledge, made a real difference.”
“Vineet and his team kept me well informed throughout the process, patiently answered all my questions, and went above and beyond to develop the right mortgage strategy and structure.”
Selected excerpts from genuine Google reviews. Individual client experiences are not guarantees of future outcomes.
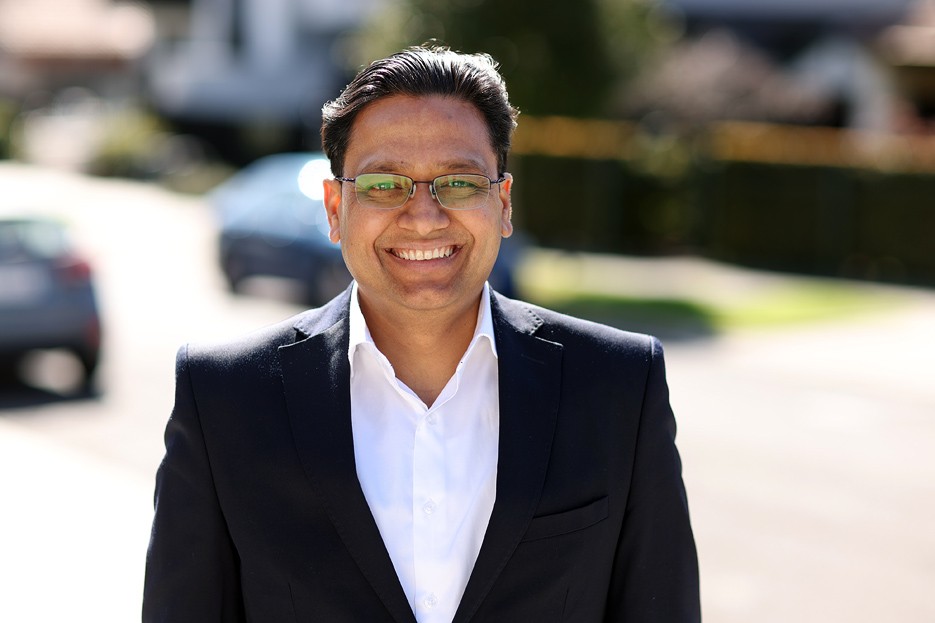
Chartered Accountant and mortgage adviser, founder of TransformBiz. Vineet spent more than 25 years in corporate finance and governance at PwC, Deloitte and Protiviti and in banking, before building a practice around one idea: structure comes before rate.
Finance by design, not by chance.
Yes, but from 10 August 2026 new SMSF borrowing can only be used for business real property, such as commercial premises used wholly and exclusively in a business. Residential property can no longer be bought with new SMSF borrowing.
Generally yes, for business real property, on commercial terms at market rent. Your SMSF accountant and licensed adviser should confirm the lease and the arrangement before you proceed.
Usually more than for residential property, and it varies by lender, property type, lease and borrower. We’ll give you a realistic range once we understand the property and your position.
There’s no single answer. It depends on your income, your business, asset protection and your plans. We set out the lending side of each option; your accountant confirms tax, and a licensed adviser covers any SMSF decision.
No. We provide credit assistance and a Chartered Accountant’s view of the numbers. Decisions about your SMSF strategy should be made with a licensed financial adviser, and we’re happy to work with yours.
An initial conversation with no obligation. We look at the property, the lease and your situation, and tell you what a lender is likely to need. Any fees are explained before you engage us.
Four quick steps, about two minutes. Tell us about the property and how you plan to buy it.